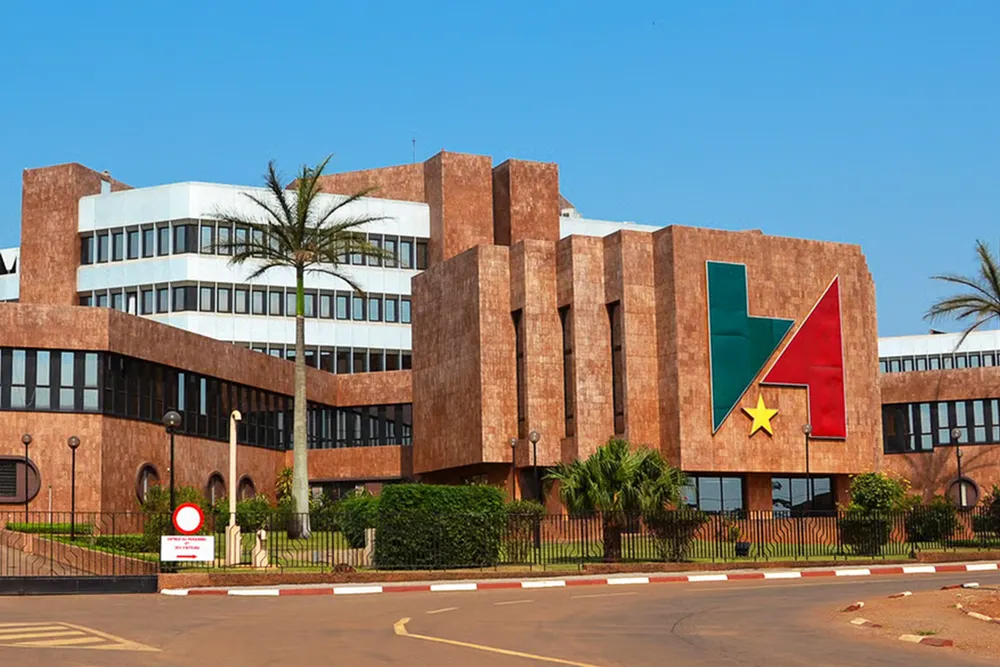
Cameroon's state oil company sits at the centre of the country's petroleum industry, public finances and energy ambitions. It's therefore difficult to regard the controversy surrounding the Société Nationale des Hydrocarbures (SNH) as merely an internal corporate dispute. The more consequential question is whether the institution entrusted with some of the country's most strategic public assets is being governed with the transparency and accountability those assets require.
That question acquired new urgency on August 19, when Africa Intelligence published an investigation reporting what it described as serious governance and accounting irregularities at SNH, drawing on an audit attributed to Jean-Marc Bell Bell of CAC International. Among the issues it reports are questions concerning corporate meetings, the accounting treatment of SNH’s investment in CSTAR, a planned refinery and strategic petroleum-storage project near the Kribi deep-sea port, board governance and transactions associated with the project’s financing.
The underlying audit hasn't been made publicly available to us, and SNH's published material doesn't independently establish every allegation reported by Africa Intelligence. But the controversy deserves scrutiny because CSTAR isn't a peripheral investment. It sits at the heart of SNH's current ambitions to expand Cameroon's refining and petroleum-storage capacity.
SNH describes CSTAR as a project encompassing a 30,000-barrel-per-day refinery and a strategic petroleum-products storage facility near the Kribi deep-sea port. SNH has put the refinery project's estimated investment cost at US$621.96 million, and has also announced a mandate to BGFIBANK Cameroon to mobilise US$210 million for the project. The distinction matters: a financing mandate isn't the same thing as financing actually disbursed or secured.
The scale of the project makes the governance question unavoidable. When a state-owned company commits itself to an investment this size, how transparent are the decisions behind it, and how effectively can the public verify them?
SNH's own financial statements illustrate why the question matters. Its 2023 annual report records consolidated assets of roughly CFAF 802 billion and net income attributable to the group of about CFAF 38 billion. It also reported more than CFAF 21 billion in taxes and a CFAF 20 billion gross dividend paid to the State. SNH isn't simply another public company, in other words. Its financial performance affects the resources available to the Cameroonian state, and its investment decisions can create exposures that ultimately land on the public balance sheet.
The International Monetary Fund has repeatedly raised concerns about SNH's direct interventions and their implications for fiscal management. In its July 2025 review, the Fund said unplanned direct interventions through SNH were "the main source of fiscal slippage" in 2024. It also said SNH direct interventions, which include emergency payments made on behalf of the government, undermine budget integrity and predictability. Cameroon subsequently committed to include in the 2026 budget expenditures previously financed through SNH interventions, and to have SNH transfer hydrocarbon-sale revenues to the Treasury after production costs.
The IMF has not, on the evidence available to us, passed judgment on the CSTAR controversy or the August audit. What matters here is different: the questions now being raised about SNH arrive against an existing international reform agenda already focused on the company's fiscal transparency and governance.
That's worth separating out clearly, because accounting, corporate governance and public-finance governance aren't identical problems. Inadequate disclosure of an investment is an accounting and reporting issue. Failing to convene required corporate meetings is a corporate-governance issue. Transactions conducted outside established budgetary mechanisms are a public-finance issue. What ties them together is whether shareholders, regulators and citizens can actually see how decisions involving public resources get made.
The harder question is whether those governance rules actually work. A state enterprise doesn't become well governed simply because it has a board, auditors, annual reports and formal financial controls. Governance becomes meaningful when those institutions can scrutinise management, challenge major transactions and demand disclosure, when decisions involving public resources can actually withstand independent examination.
The reported findings deserve scrutiny, but they shouldn't be treated as established proof of wrongdoing.
Africa Intelligence reports that SNH had gone several years without holding the corporate meetings required to approve its accounts. We haven't found sufficient public documentation to independently verify that claim. It also reports concerns surrounding the accounting of SNH's CSTAR investment and transactions associated with the project's financing, including an alleged US$10 million transaction reportedly routed through Dubai. We haven't independently verified that transaction from SNH's publicly available material.
What is publicly documented is that CSTAR has a formal corporate structure and that SNH has publicly disclosed its involvement in the project, including its participation in its governance and financing arrangements. SNH's published material records that CSTAR's inaugural general meeting was held in Dubai on April 25, 2025.
That leaves several questions more useful than political speculation. How exactly is SNH's CSTAR investment reflected in its accounts, and what did the audit reportedly identify? Which financing transactions have actually been completed rather than merely announced, and how will management respond? What mechanisms exist to ensure major investments by a state-owned oil company remain subject to meaningful board and shareholder oversight?
These are economic questions before they're political ones. Lawyer Akere Muna has characterised the reported findings as evidence of opaque, off-budget operations, and warned of potential implications for Cameroon's sovereign creditworthiness. Those are his characterisations, not independent confirmation of the underlying allegations. The more durable concern is institutional: whether Cameroon's systems for supervising petroleum wealth are robust enough for the scale of the resources being managed.
Cameroon needs SNH to generate revenue and support energy security, and to help finance strategic infrastructure as the country industrialises. But the more economically consequential SNH becomes, the less room there should be for ambiguity over how its decisions are made, how its investments are recorded, and who is ultimately accountable for them.
The CSTAR controversy may ultimately concern one project and one audit. It may also expose something larger, though: the gap between institutions designed to provide accountability and institutions strong enough to actually enforce it.
Cameroon wants SNH to operate at the scale of a sophisticated investment institution. It should therefore expect SNH to be governed with the transparency of one. That's ultimately what the CSTAR controversy puts under scrutiny, not merely one refinery project, but the credibility of the institutions managing Cameroon's oil wealth.